Agents can reduce friction by making online marketing align with room size, light and walkability
Article Summary
The piece explains why photo forward staging can backfire when rooms feel cramped or darker in person. It recommends staging to clarify purpose, improve movement and keep marketing aligned with the real experience. AI Summary
Professional photography has become an essential part of selling a home. Agents invest in lighting, furniture placement and carefully selected angles to make listings stand out online. But there is a problem with focusing too much on how a property looks through a camera.
A home can look beautiful in photographs and still disappoint buyers the moment they walk through the door. The purpose of staging should not simply be to produce attractive listing photos. It should be to help buyers understand the space, recognize its potential and imagine living there.
A beautiful photo doesn’t always mean a functional home
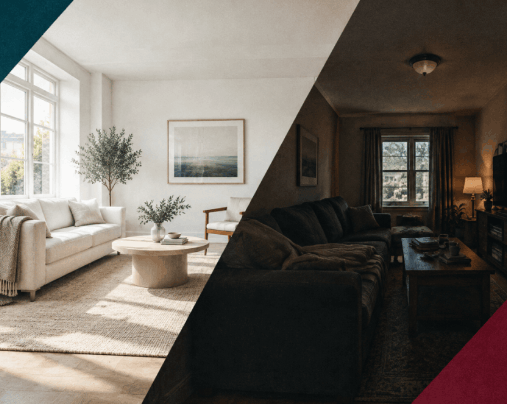
A large sectional sofa might look impressive in a listing photograph. But if it makes the living room difficult to walk through, buyers are going to notice. The same goes for oversized dining tables, crowded bedrooms, and decorative furniture that serves no practical purpose. These choices can create attractive images while making the actual rooms feel smaller and less comfortable.
Buyers aren’t simply evaluating furniture or decorations. They’re thinking about where their own belongings will go, whether their family will have enough space, and how the house will function on an ordinary day. Good staging should make those questions easier to answer.
Staging should solve problems, not hide them
One of the biggest misconceptions about staging is that every room needs more furniture, more decorations, or expensive upgrades. Sometimes the opposite is true. A crowded living room might benefit from removing a chair rather than purchasing new furniture. A small kitchen can feel more functional when countertops are cleared. An awkward spare bedroom might become easier to understand when presented as a simple home office. The goal should be to identify what might make a buyer hesitate and address it before the property reaches the market. This also requires honest conversations with sellers.
Homeowners often have strong attachments to their furniture, decorating choices and the way they’ve organized their homes. What works for them, however, might not work for the next owner. Agents need to explain that preparing a property for sale isn’t about judging personal taste. It’s about creating an environment where more buyers can imagine their own lives.
Don’t create expectations the home cannot meet
Another issue is the growing gap between online presentation and in-person experience. Wide-angle photography, carefully controlled lighting, and virtual staging can all be useful marketing tools. However, they become counterproductive when they create unrealistic expectations.
A buyer who expects a spacious, naturally bright living room might feel disappointed when the actual room is smaller and darker than anticipated. That disappointment can influence how they perceive the rest of the property.
Agents should therefore evaluate listings from two perspectives. First, how will the home look online? Second, will the actual experience support what the photographs promise? Both questions deserve equal attention.
The showing matters more than the photograph
Before putting a home on the market, agents should walk through the property as a first-time visitor would. Consider how easily people move between rooms, whether furniture blocks important features, and what buyers notice immediately upon entering. These details rarely require major renovations. Often, small adjustments improve the entire experience.
Professional photography gets buyers interested in a property. Thoughtful staging helps that interest survive the showing. The most effective listings aren’t necessarily the ones with the most expensive furniture or elaborate decorations. They’re the ones that present a home clearly, comfortably, and realistically.
At the end of the day, agents aren’t selling photographs. They’re selling places where people expect to live. And the experience of walking through a home should always matter more than how impressive it looks on a screen.
Greg Dallaire is the Owner and Realtor at Dallaire Realty, active in residential real estate since 2006.
This column does not necessarily reflect the opinion of HousingWire’s editorial department and its owners.
Greg Dallaire is the Owner and Realtor at Dallaire Realty (https://www.dallairerealty.com/) , active in residential real estate since 2006. He also brings interior design and home staging experience, helping sellers present homes in a way that improves flow, highlights key features, and creates a stronger connection with buyers.see full bio
For decades, shoppers learned that the way to find the products online you’re most interested in is to type two or three keywords into a search box, scan a grid of products, adjust the filters, and check the products or try another query.
Generative AI is changing that behaviour. Consumers can increasingly describe a problem, ask a question and expect the ecommerce platform to deliver up the exact product and configurations they want. For online retailers, search is becoming less like a database lookup and more like a digital sales associate.
Ecommerce shops and retailers have reason to pay attention. A search query is one of the few moments when customers tell a store, in their own words, exactly what they want, something called purchase intent. While much of that information has historically not been put to good use, AI can connect those queries to recommendations, inventory, customer service and advertising.
The stakes rise further as shopping migrates into ChatGPT, Google AI Mode, Gemini and other AI interfaces. More importantly, these AI tools can do so without the interaction or visibility of the ecommerce shop.
The change is already showing up in traffic. Adobe reported that generative AI services drove almost a 700% year over year increase in traffic to U.S. retail sites during the 2025 holiday season. Shopify says AI driven traffic to its merchants grew eightfold year over year in the first quarter of 2026, with orders attributed to AI powered searches rising nearly thirteenfold.
Then comes a thornier problem: who owns the shopper? If consumers increasingly begin with ChatGPT, Gemini or another AI assistant, the retailer may no longer control the first interaction. The store could become a data source behind somebody else’s interface.
Who owns the customer relationship when search becomes a conversation? Does the retailer still control product discovery? Does an AI platform become the new storefront? Or does commerce split into layers, with AI agents controlling the conversation and retailers competing to make their catalogues intelligible to those agents?
Moving From Keywords To Intent
Paulius Nagys, co-founder and head of growth at Kaunas, Lithuania-based AI search and product discovery company LupaSearch, thinks the answer starts with the product data underneath it, much less glamorous than the chatbot.
We have spent decades of web experience learning how to communicate with machines to get what we want.
Want running shoes? Type “men’s running shoes.” Need a drill? Search “cordless drill.” To narrow down and get to what we want to buy, we’ve learned to strip away context and reduce an idea to the handful of words most likely to produce a useful result.
Nagys thinks that approach is now breaking.
“People are moving from typing keywords to just asking a full question and expecting an answer,” he said in a one-on-one interview. “Not a page of results to sort through themselves. So the search box has to actually answer now, not just index.”
Paulius Nagys, co-founder and head of growth, LupaSearch
Domas Urbonas / Urbongraphy / LupaSearch
Google is already changing behaviour. The company says its AI Mode response box has surpassed one billion monthly users in 2026, and its queries have more than doubled every quarter since launch. Google’s redesigned Search experience gives people more room to describe complex requests and keep asking follow-up questions.
Salesforce has seen the change in shopping behaviour too. Its 2025 Connected Shoppers research found that 39% of consumers had used AI for product discovery, rising above half among Gen Z respondents.
Caila Schwartz, Salesforce’s director of industry insights, framed the challenge this way: “The best-performing content anticipates what a shopper is trying to solve, not just what they’re searching for.”
The difference is pretty important in terms of connecting the shopper to what they want. In the past, retailers depended on the shoppers knowing what product will meet their needs. For example, a shopper typing “cordless drill” made life easy for the retailer. But what if the question is “What do I need to hang shelves on a concrete wall?”
The customer may need a drill, masonry bit, anchors and screws without mentioning any of them. Finding the right answer requires more than matching words in a query with words on a product page. The system has to infer the job.
That starts to look less like fulfilling orders and more like consultative selling.
The Search Box Is Starting To Look Like A Salesperson
Nagys expects ecommerce search, product discovery and customer service to begin bleeding into one another.
A shopper might ask about a product, then whether it is available nearby, then whether another alternative would work, then how returns work. Today those requests can send someone bouncing between search, product pages, product reviews, FAQs and customer support. In the past that has meant lots of open tabs, lots of searches and cutting and pasting while trying to figure it all out.
Nagys expects that behaviour to change. In our interview, he described a future ecommerce experience built around questions and answers rather than isolated searches.
Google is heading down a related path. At the National Retail Federation conference in January, CEO Sundar Pichai described AI moving through product discovery, purchasing and customer experience. Google has been working with retailers on shopping agents that can answer detailed questions and make personalized recommendations.
Amazon is already experimenting in the wild. The company said Rufus, its AI shopping assistant, was used by more than 300 million customers in 2025 and contributed nearly $12 billion in incremental annualized sales. Rufus answers questions about products, and Amazon’s Buy For Me capability can purchase certain products from other online stores.
Not Every Search Needs An LLM
While AI is part of the equation and owning the conversational experience might be critically important, the catch is that someone has to pay the inference bill. Running conversational AI at retail scale can get expensive quickly.
A small merchant may process a manageable number of searches. A global retailer can handle millions of queries against catalogues containing hundreds of thousands or millions of SKUs. Nagys argues that sending every one of those requests directly through a large language model makes little economic sense.
Nagys says, “Not every AI problem needs an LLM solution.”
His company’s LupaSearch solution takes a more selective approach, he said. Conventional retrieval handles queries it can resolve efficiently. Heavier model calls can be reserved for cases where those methods struggle, including unusual natural language requests or searches that produce no useful results. Those interactions can then feed improvements back into the search system.
From this perspective, there isn’t one AI sitting behind modern product search. A retailer might use semantic vectors to understand synonyms, recommendation models to predict what someone could want next, image recognition to extract attributes missing from product descriptions and an LLM when cheaper methods fail.
And there really is no need to call it “AI search” if customers have questions and retailers want to provide answers. The technology obscures the questions merchants actually need answered. Does it work? Is it fast? What does each query cost?
Nagys has little patience for the industry’s loose vocabulary around AI. In our interview, he compared the current excitement to the dot-com era, when attaching the latest technology to a business could become more important than explaining what the technology actually did.
Algolia has landed on a hybrid architecture too. Its commerce technology combines keyword and semantic retrieval with conversational systems grounded in merchant data. Its Agent Studio product puts cost controls next to AI agent capabilities, a reminder that impressive demos eventually meet operating budgets.
It’s Still All Data
Regardless of the technology approach, all of this is based on having good quality data. Bad data or bad connections make even the most robust catalogue impenetrable for conversational assistants.
For example, if you ask an AI shopping assistant for a waterproof commuter jacket under $200, that might sound simple. But behind that request sits an ugly data problem.
Does the retailer reliably record waterproofing? Is “water resistant” treated differently? Are sizes normalized? Does the system know which colours remain in stock? Can it distinguish a winter shell from a light rain jacket? Can another AI system access any of that information?
“Is your catalogue well prepared for this?” Nagys asked during our conversation. He described structured product data as the foundation on which more sophisticated AI functions can be built.
Shopify is attacking that problem at an enormous scale. Its Catalog API turns product information from millions of merchants into structured data that software can query. Shopify’s Universal Commerce Protocol, developed with Google, gives agents a standardized method for interacting with merchants through discovery and transactions. In 2026, Shopify opened more of that agentic commerce infrastructure to developers, including access through a public Model Context Protocol endpoint.
Algolia released its own MCP server in September, designed to connect systems such as ChatGPT, Claude and Gemini with live product information, including inventory, pricing and merchandising rules.
The issue with inventory is also important when companies are using their SKUs to get search visibility, even if the items are not in stock. This might work for an SEO-controlled world but it is much more frustrating when agents are trying to connect buyers with real intent to products they can purchase today.
Imagine that I want a computer with a particular amount of memory and it keeps appearing out of stock. Today I might search Amazon, then Micro Center, then Newegg, opening tabs and repeating roughly the same query.
A different model would let my AI assistant query participating catalogues for me. I can describe the machine once and let the agent find who actually has it, at what price and under what delivery terms. In that world, the retailer’s search visibility matters less. The quality and accessibility of the data underneath it matters a lot more.
This is where retailers could lose control.
A customer can tell an AI assistant, such as a Google AI Mode conversation or ChatGPT chat to “Find me a waterproof commuter jacket under $200 that will arrive by Friday.”
The assistant will decide which brands appear, which retailers get queried and which products make the final cut and are surfaced as the best option that is available immediately within the customer’s budget. The customer never needs to visit ten websites or click through unavailable options.
Complicating this shift is advertising. Retailers know that search intent is highly valuable information. Advertisers want to tap into this by paying AI and search companies to steer transactions their way.
The biggest AI platforms are moving in that direction. Google is testing ads in AI Mode that use Gemini to pair sponsored products with explanations tailored to a shopper’s question. OpenAI has gone further, launching ads in ChatGPT and building a self service advertising platform with cost per click bidding.
This brings into question what should the customer see in responses? The best match or a sponsored product? AI can make that decision with far more context than traditional keyword advertising ever had. When an AI assistant becomes part search engine, part salesperson and part advertising channel, the line between answering a shopper’s question and monetizing the shopper’s intent becomes critical.
Nagys does not think that means retailer websites simply disappear. He points to Google Shopping as a useful precedent. Aggregators became powerful, yet merchants remained part of the transaction.
His bet is that retailers need infrastructure capable of serving the shopper wherever the request originates.
“We’re not trying to be the agent someone talks to,” Nagys said of LupaSearch. “We’re the layer that makes a retailer’s catalogue actually readable by whatever agent shows up.”
That could be LupaSearch’s own search interface. It could be Google. It could be a customer’s ChatGPT session or an AI Mode interaction. The front door becomes less predictable, but regardless, ecommerce shops and retailers need to be ready for the new reality.
Hunter Arbaugh brings in more than $5 million a year in a one-person business selling billboard ads from his home office.
Arbaugh, 33, started his business, Supper Club, in August 2024, investing about $2,500 to form an LLC and launch. Working for both billboard companies and then an agency that bought the ads, he found the buying process dated and unduly complicated, with a web of fees and charges.
He decided to do something about it. Leaving his agency job, he developed an all-inclusive solution, with one price covering both the ad and production, installation and shipping. He tapped connections he’d built over seven years in the industry to spread the word and gave the business an unconventional name, Supper Club, to attract customers who believed in creative advertising, rather than AI-written billboards. “There’s so many very tech-forward companies in my industry,” he says. “I wanted to set myself apart a bit.”
Arbaugh brought in less than $1 million the first year, but sales kept mounting. He handles virtually every piece of the business himself, as a solo entrepreneur, augmenting what he can do using AI-powered tools. For instance, after a lot of experimenting, he used vibe coding to create his own customer relationship management software (CRM) using a platform called Base 44. That makes it easier to customize his sales presentations for each client and keep himself available to clients when they need him. Word of mouth has driven his growth. “I don’t need every advertiser to know about my company,” he says. “Clients keep coming back for more, and they bring their friends along for the ride, too.”
For his back office, he uses Collective, an AI-native financial operating system that targets “businesses of one” with services such as business entity formation and bookkeeping. He used it to help him move the business recently from Los Angles to Louisville, Ky., when he relocated.
Arbaugh is among a growing number of one-person businesses bringing in $1 million or more in annual revenue. Many are extending what they can do by using digital and AI tools and tapping help from contractors and platforms that tackle tasks they might otherwise have had to do themselves.
Hunter Arbaugh saw a better way to sell billboard advertising. He turned it into a million-dollar, one-person business. Alfonso Cantarero Jr.
Among the nearly 32 million nonemployer businesses in the U.S. in 2024, 130,356 brought in $ 1 million in revenue or more in 2024, up from 117,060 in 2023, according the most recent data from the U.S Census Bureau. The largest category of these businesses is in construction (20,986 businesses), followed by professional services (18,378), retail trade, including ecommerce (17,101) and wholesale trade (11,664). Arbaugh is in an elite revenue category: Just 1,051 brought in $5 million and up, in 2024, up from 905 in 2023, and most are financial firms, such as hedge funds.
Collective announced this morning that it has raised $100 million to fuel additional development of its agentic financial operating system for solopreneurs, as well as product development in banking and insurance. The round includes a $40 million Series B round led by General Catalyst, QED and Gradient Ventures, with Intuit Ventures, FT Partners and SemperVirens and $60 million from General Catalyst’s Customer Value Fund (CVF), to fuel customer acquisition.
“It is funding us to invest back into the tooling so we can provide every solopreneur with their own finance department,” said Hooman Radfar, co-founder and CEO of Collective. The “self-driving” platform provides AI tools with access to human experts. In addition to entity formation and bookkeeping, it offers invoicing, payroll, taxes and access to business and health insurance, charging between $199 a month and $349 a month depending on the business size. The company says it is growing 127% year-over-year.
Hooman Radfar, CEO and co-founder of the the agentic financial operating system Collective, just raised $100 million to grow the platform. Collective
“With CVF, we look for companies with high-quality unit economics and a large market opportunity,” said Pranav Singhvi, Partner and co-head of CVF, General Catalyst. “We see solo businesses as one of the most dynamic segments of the economy, and we expect that trend to accelerate as AI advances. Collective has built a one-stop shop for their financial needs. Their vision and track record make Collective exactly the kind of company CVF was designed for.”
Taylor Crane, a serial entrepreneur in the tech space, started his business, Fractional Jobs, in 2020, using Collective to set up his business and handle his bookkeeping. Fractional Jobs caters to professionals who work as part-time executives on a recurring basis for multiple companies. After a year as a fractional head of product, the entrepreneur, based in Brooklyn, N.Y., well understood the challenges in the space, such as difficulties in finding work and complexities in business operations.
Determined to solve these problems for other fractional executives, he started his solo business as a self-service job board. He soon discovered that the executives needed a more curated, white-glove approach to matchmaking and shifted in that direction, connecting the executives to his network of early-stage startups, small businesses and nonprofits. He spends a lot of his time networking to find companies seeking fractional help and doing Google, AI and LinkedIn searches to find other opportunities for his subscribers. It’s become a calling. “The mission of the company is to accelerate the fractional work movement,” he says.
Along the way, the newsletter where he shares the job opportunities took off, with an open rate of about 65%, and has grown to a subscriber list of nearly 50,000 fractional executives, with 3,000 people joining every month. “Every fractional executive is looking for new opportunities, always,” Crane says. Companies targeting the subscribers began advertising, which added to his revenue. This year, he anticipates revenue in the $600,000 to $1 million range.
The solopreneur trend is accelerating around the world. The recent Stripe Report says that AI-native solo founders brought in nearly twice the revenue of other solo-founded startups. The report tracks the growth in this population but does not disclose the number of businesses in these categories. It notes that B2B businesses, those using AI and those who sell globally have an edge, as do those who master customer retention.
Radfar, at Collective, believes the trend is only going to accelerate with the growth of AI tools, which is allowing many entrepreneurs to start and scale self-funded businesses at an unprecedented rate, bypassing the challenge of raising venture capital altogether. “They want to do their own thing, and they can with AI,” he says.
Meanwhile, many people in traditional jobs are now worried about the risks of being an employee in an age of AI, with many big organizations announcing they are growing without adding jobs, or laying people off. These workers are saying, “Wait a minute! I don’t need a big company anymore,” Radfar says. He believes the quest to realize the potential of these businesses is going to fuel future growth of the platforms that serve them. “This race is going to continue and continue,” he says.
Feature image credit: Taylor Crane, a former fractional executive, started his newsletter, Fractional Jobs, after noticing how challenging it was for fractional executives to find their next project. Fractional Jobs
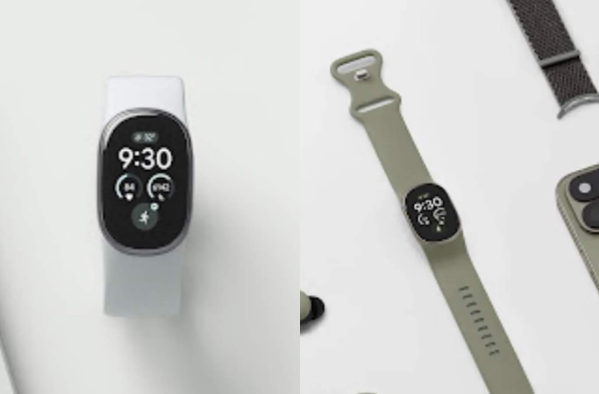
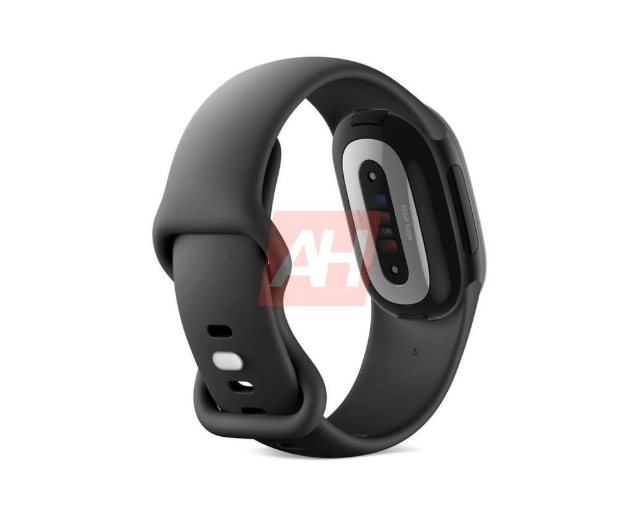
Within days of the Pixel 11 series and Pixel Watch 5 launching, online marketing images from Google showed off a mystery wearable device that looked like a mix of a Pixel Watch and a smaller fitness tracker. Google wouldn’t talk about the device at that time, but we’re pretty sure we saw it cruise through the FCC last month on its way to launching here in the near future.
This weekend, retail marketing images have surfaced for the device and it is apparently called the “Google Fitbit Edge.” A launch date and price are not yet known, but if retail listings are showing up for people to capture, we should know both before long.
What is the Google Fitbit Edge?
The image at the top of the post is the device. Those images were captured when the device first showed up online and this new info dump confirms the design.
The Fitbit Edge will reportedly not run Wear OS, which makes sense as a smaller fitness tracker with a display. It has compatibility with both Android and iOS, so this will likely just pair to the Google Health app like we see with the Fitbit Air.
It’ll have up to 7 days of battery life, show some info from Google Maps, allow you to control media and music, and attach to Find My Phone for tracking. It connects over Bluetooth and can show notifications.
It will also apparently have built-in GPS, elevation tracking, and automatic activity recognition. The health sensor on the back (see below) looks just like the sensor on the Fitbit Air.
As for colours, there should be black (Obsidian), green (Olive), and orange (Canyon?).
Fitbit Edge release date, pricing
OK, so what about pricing and a release date? We don’t know yet. If retail imagery like this is showing up, this thing should be close to launching, possibly within the next month.
As for pricing, since it has a display and more capabilities than the Fitbit Air, I’m going to assume it’ll cost more than the Fitbit Air, which retails at $99. However, this isn’t a full-blown smartwatch, so it should also come in well under the Pixel Watch 5 which starts at $399.
Will the Fitbit Edge cost $150? $200? Take your best guess.
Budget season has arrived on shakier ground than usual. Inflation is sticky, consumers are pickier and CFOs are asking a question that many platform dashboards can’t answer: What revenue did this spend actually cause?
Marketers have moved beyond last-click, and most feel good about their measurement. But I find that few can see how their spending actually performs across channels.
Here are my five predictions for how that gap closes in 2027.
1. Platform-Reported Numbers Stop Counting As Evidence
2026 showed how fast a platform can rewrite its own scorecard. Meta removed its seven-day and 28-day view-through windows in January, then redefined what counts as a click in March. Many advertisers saw reported conversions fall 15% to 40% overnight, with no change in real performance.
Yet Winterberry’s September 2026 survey found that 93% of brands rely on platform-native tools, and 84% call them a core part of their measurement stack. More than three-quarters say they’re satisfied with the in-channel incrementality those tools report.
But I don’t think that satisfaction would survive a thorough review. A platform is graded on the metrics it reports about itself, and it will claim credit for a sale whether its spend caused it or not.
My prediction: By the end of 2027, the number marketing reports will be incremental return on ad spend (iROAS), not platform-reported return on ad spend (ROAS).
2. Traffic Stops Being A Proxy For Demand
When an AI Overview appears, organic click-through rate has fallen from roughly 1.76% to 0.61%. On mobile, most Google searches now end without a single click. As platforms take over the mechanics of media buying, an advertiser’s edge shifts to the data and information outside those mechanics.
Teams that read a traffic decline as a demand problem are likely misdiagnosing it. Often the demand didn’t disappear, only the click did.
I foresee sessions and click-through rate (CTR) being demoted from headline key performance indicators (KPIs) to supporting signals. Geo-lift (which measures the incremental impact of marketing by comparing outcomes across geographic areas), holdout tests and causal media mix modeling don’t care whether a customer clicked a blue link or read an AI summary.
These can all better measure whether the spend moved the outcome.
3. Influence Moves To Surfaces With No Click To Count
Morgan Stanley estimates agentic shoppers could account for as much as $385 billion in U.S. e-commerce by 2030. ChatGPT’s self-serve ads platform crossed a $1 billion annualized run rate within months of opening to all U.S. businesses. Social is becoming a purchasing channel too, yet DHL found that 63% of e-commerce businesses sell through social while only 45% of shoppers buy there. People discover on one surface and purchase on another.
According to another Forbes Council piece, the hard question ahead is no longer how to get seen, but how to get believed. Belief is built through creator reviews, comment threads, group chats and AI answers, and most of that never produces a trackable click.
I believe a new channel’s self-reported attribution will soon count for nothing on its own. Every new surface will need to pass a bounded incrementality test before it earns an always-on budget.
4. Unified Measurement Becomes The Operating Standard
Winterberry’s data shows an industry that has outgrown its old methods but not yet its silos. Only a third of enterprise brands still use first- or last-click attribution. Far more use marketing mix modeling (71%), data-driven attribution (62%) and incrementality testing (52%).
The gap is in putting them together. Unified marketing measurement is a leading priority for 83% of brands, but only 9% say they can practice it “extremely well.” Cross-channel optimization was the top measurement priority, chosen by 40% of respondents. That ranked ahead of data aggregation (33%) and incrementality and causality (31%).
They want the methods to agree with each other and produce one answer about where the next dollar should go.
That’s why I see standalone attribution tools losing to systems that calibrate media mix modeling (MMM), incrementality testing and causal attribution against each other. That calibration is what makes the output audit-grade.
5. Measurement Starts To Act, With Humans Setting The Guardrails
Every major platform is automating the buying side. Google is migrating search campaigns into AI Max and plans to bring Dynamic Search Ads into the same framework in 2027. When the platform runs the mechanics, the advantage goes to the team with better inputs and better judgment about what comes back.
Winterberry’s research suggests that gap is still wide. AI is already present in measurement at most brands, but it remains peripheral for many of them. Only 16% say AI plays a central role in measurement, while just 18% believe they have the people and expertise optimally deployed. The result is a paradox: AI is becoming easier to deploy at the same time that interpreting its output remains a scarce capability.
Dashboards tell you what happened and leave a person to decide what to do. Agents that act on a causal model can close that gap. They can reallocate budget, pause spend that isn’t incremental and flag drift—all within limits a human sets.
My prediction is that the strongest teams in 2027 won’t hand measurement or strategy to AI. They’ll give the measurement model the routine reallocation and reporting work, and keep people making the strategic calls, informed by real data.
Finalizing A Plan
Before you finalize your 2027 plan, here are three changes to consider:
1. Re-baseline every platform metric against post-change numbers. Comparing this year’s Meta or Google figures with last year’s isn’t a like-for-like read.
2. Split iROAS from reported ROAS for each channel. The gap between them is where next year’s budget reallocation opportunity lives.
3. Fund one bounded test in a new surface. Test something like ChatGPT Ads, with an incrementality read before you scale it.
The platforms will keep changing their rules, and AI will keep intercepting more of the click. The answer to both is to build your plan on evidence that doesn’t move every time a platform updates its algorithm.
Its AI Mode isn’t the cash cow it hoped it would be.
Woe is Google. After it starved out publishers with its AI features, it’s now getting a taste of its own medicine.
Shares of its parent company Alphabet took an over 11 percent nosedive on Wednesday, after it disclosed that its AI search features are raking in less money than its traditional search ad model. The steep correction wiped out more than $500 billion in market value.
In its Q3 report, Google reported a quarterly revenue of $127.6 billion, a 25 percent year over year increase. But it’s also spending more, with capital expenditures more than doubling from last year to $51.4 billion, largely thanks to its massive AI investments.
Meanwhile, the growth of its revenue from search seems to be tapering off. It reported a 12 percent year-over-year increase to $63.3 billion, which is less than the 14.5 percent growth it reported in the same period last year.
That’s despite Google Search fielding more queries than ever. Google chief business officer Philipp Schindler admitted in an earnings call, per Search Engine Land, that this was because of “lower monetization we’re seeing in AI Mode,” its AI-powered search experience that works more like a chatbot instead of showing the traditional ten blue links.
It’s an ironic, but perhaps not unforeseen, downturn for Google. When ChatGPT became global phenomenon in late 2022, questions were soon asked regarding if a shift to using chatbots to obtain information over a traditional search engine would topple Google’s ludicrous advertising empire, which earns the company hundreds of billions of dollars each year.
Google responded by developing its own AI features, including its notoriously unreliable AI Overviews, and prominently integrating them into its search engine. This came at the expense of the websites and publishers that its AI models were pilfering from: users were happy to read error-plagued summaries instead of visiting the websites that contained the original information, depriving these sites of clicks and ad revenues. Despite Google’s repeated claims to the contrary, multiple studies have demonstrated that AI Overviews have destroyed click-through rates.
This has had a disastrous effect on the media landscape, with data compiled by Axios showing that the number of visits to top news sites plummeted from over 70 million visitors a month in July of 2024 — the year that Google launched AI Overviews — to just over 47 million in July of 2026. Media leaders who responded to a Reuters Institute survey are grim about the future, predicting traffic to their websites to fall by nearly half over the next three years amidst this AI-dominated paradigm.
Now, Google is getting a taste of this too, earning less advertising dollars from its AI Mode than from the traditional search that it is so eager to abandon. It seemingly hasn’t considered what comes next after the websites it earns money off of all go out of business.
Chief business officer Schindler, though, was adamant that Google will soon start squeeze more money out of AI Mode.
“On AI Mode, many of these queries are upper funnel queries, allowing us to capture new, high-value commercial intent,” he argued. “In addition, the majority of AI Mode queries are incremental, creating more monetization opportunities over time.”
I’m a tech and science correspondent for Futurism, where I’m particularly interested in astrophysics, the business and ethics of artificial intelligence and automation, and the environment.
After embracing the use of AI, the platform now appears to be shifting its strategy.
On the platform, users can now flag a post they believe shows heavy AI use. This feature comes on the heels of the company’s embrace of AI, in which it added AI tools to help members rewrite posts and content.
Now, it seems to be cracking down on AI use.
“AI slop is a top priority for all of us. We really care about this,” Hari Srinivasan, the company’s chief product officer, wrote in an update. “People come to LinkedIn to connect with real people and share their real perspectives, ideas and expertise.”
In this effort, the company said it will continue to expand profile and page verification in order to further identify members and clarify who is writing the content users are reading. LinkedIn will also remove the “enhance your post” AI feature users see when they write a post or message. The button will be replaced with a tool that proofreads content—but does not change a writer’s voice.
“We asked ourselves why do people post with AI anyway? The answer is LinkedIn isn’t a one-word kind of place and they feel more confident running their posts through AI,” said Srinivasan.
When reached for comment, LinkedIn directed Inc. to Srinivasan’s post.
Writing styles
As the use of AI rises, many have turned to tools to help “enhance” their writing. This in turn created a new phrasing—”AI slop”—referring to an overly robotic and keen-toned style of voice that feels generic and low quality.
“The irony here is that LinkedIn’s algorithm is quite elusive, but over the past year it rewarded the type of LLM speak that has become prominent across all socials, especially LinkedIn,” Matt Maher, CEO of M7 Innovations, told Inc.
He added that those type of posts were often successful on the platform. “That one sentence per line, staccato-type speech, ‘not X but Y,’ overly tech-bro copy mansplaining is what actually worked and pumped you up in the algorithm,” he said. “Now they realize they not only gave everyone the tools to create the AI slop they want to eliminate, but they rewarded it in the algorithm and are now desperate to quickly unwind that as fast as they can.”
According to Kinsta, only a small percentage of LinkedIn users actively post on the platform. However, those that do often do so on a regular basis. In order to increase the amount of content, such users may turn to AI tools for assistance. Per a report from 404 Media, between 30 and 41 percent of content on LinkedIn was generated by AI.
For many, the crackdown is a welcome change.
“I see this as highly opportunistic, as someone who uses LinkedIn as a main platform for our thought leadership and has always personally written every post. I now see a path where I can completely speak the algorithm’s language and get amplified,” Maher told Inc. “The larger signal here is that we’re entering the artisanal era of the internet, where every platform realizes that humans, indeed, do not want to see AI slop from one another.”
Once an obscure job title, creative technology is becoming a new way of working, and a core capability inside modern product teams. Soon, many of us may be working this way.
As AI collapses the distance between idea and implementation, companies are looking for people who can move across design, code, systems, and storytelling.
Let us begin by disambiguating the Creative Technologist role. Everyone references it as though we all know what it means. But when I ask people to define it — with specificity — most cannot.
And it’s understandable, the role is legitimately hard to pin down. It has existed for decades, mostly in advertising agencies, research labs, and experiential studios. It has also gone by many names: UX engineer, design technologist, creative developer, UX prototyper, and design engineer. The taxonomy is a mess. Even people who hold the title admit it can sound entirely made up.
But the Creative Technologist is having a renaissance. The role is being pulled from the artistic margins into the center of the machine, and understanding its origin story and direction tells us something about where many creative careers are going.
So let me try to disambiguate it.
Instead of beginning with definitions, let me start with a person.
On a recent Google Flow creator community call, the guest was Tina Tarighian, a Senior Creative Technologist at Google Creative Lab in New York. Her first-person essay, “WTF is a Creative Technologist?”, published by Will Zimmerman’s 3rd Space, is one of the clearest accounts of the role I have read. If you read one other piece on this subject, make it that one.
Her path: a nationally ranked competitive debater in high school. A political science major who thought she might become the next Hillary Clinton. A computer science degree that made her “actually study, sob, and then study some more.” A hedge-fund internship in Tokyo that felt like wearing someone else’s shoes. A psychic who pulled her off the street to tell her she was in the wrong career.
Then a net artist in Greenpoint taught her JavaScript. She was broke enough to walk 45 minutes to his studio rather than take the train. She began cold-pitching companies with creative technology ideas. Her first paid project was a virtual try-on filter for a compression-underwear brand. She was paid almost nothing and remained, in her words, “insufferably giddy for weeks.”
Image credit: Technosphere by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
She cold-messaged a musician the day before he started a band and ended up live-coding visuals at its debut show. One project turned into ten: a New Museum residency, fashion-show installations, gallery work, and her own runway shows. When she missed her no-contact ex-girlfriend, she built an email lottery with a tiny chance of actually sending her note. Five million people saw it, and people in more than 100 countries used it.
Now she works at Google Creative Lab, demonstrating tools built over a weekend to arenas of thousands, collaborating with Paris Hilton on ADHD-friendly apps using Gemini, and presenting on the main stage at Google I/O.
Here is how she describes the actual work:
“We are writing the first draft of what a technology means, sitting with something new before the obvious use cases have had a chance to calcify, and trying to find something meaningful in it.”
That is the role: writing the first draft of what a technology means.
The two ends of the spectrum
Tina maps the field better than any formal taxonomy I have found.
On one end is the commercial version, shaped by the dot-com boom, when companies needed people who could “talk to people and computers with the same suavity.” Some lean toward hardware, some live in the browser, and some build strange physical objects that end up in advertising campaigns. The through-line, in her words, is that “they’re technical enough to build and perspicacious enough to know what’s worth building.”
On the other end are people using technology primarily as an artistic medium. Think of Refik Anadol turning data into large-scale immersive environments, generative systems that feel alive, or Tina’s email lottery: code used as emotional expression. “What we all have in common,” she writes, “is that we are using technology as our primary medium to say something, not to ship products.”
Image credit: ESC by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
“I am an artist, and just like a painter’s medium is the full range of paint types and canvases, my medium is technology itself.”
Neal also created A Creative Technology Taxonomy, a large map of what a senior creative technologist might need to understand, from projection mapping and sensors to game engines and machine learning. Not everything needs to be mastered. The value of the map is that it provides a knowledge foundation for making informed choices about which technologies serve which experiences.
So when someone asks what a Creative Technologist is, the sincere answer is: someone whose medium is technology itself. Sometimes that medium is applied to commerce, sometimes to art, and often to an in-between space without a clean name.
A brief history: 60 years of the same person with different names
The thing that gets lost in the “hot new role” discourse is that this archetype is not new. Its origin story goes back six decades, and tracing it reveals something important about where it is heading.
1966: the founding moment. Bell Labs engineers Billy Klüver and Fred Waldhauer teamed up with artists Robert Rauschenberg and Robert Whitman to stage 9 Evenings: Theatre and Engineering at the 69th Regiment Armory in New York. Ten artists, including John Cage and Yvonne Rainer, worked with more than 30 Bell Labs engineers and scientists. The performances used closed-circuit television, infrared cameras, Doppler sonar, and other emerging technologies. The collaboration led to Experiments in Art and Technology, a nonprofit built around pairing artists and engineers. This is one of the clearest institutional origin points for creative technology.
1973: the academy takes over. Muriel Cooper co-founded the Visible Language Workshop at MIT, exploring how computation could transform graphic design, typography, and publishing. The workshop later became one of the founding research groups of the MIT Media Lab. The question moved from “Can artists use technology?” to “Is computation itself a design medium?”
Image credit: Blend by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
1996–2001: the medium gets its language. John Maeda led the Aesthetics + Computation Group at the Media Lab and argued that designers should understand the computer as a medium, not just a tool. His Design by Numbers project taught programming to visual artists. Two of his students, Casey Reas and Ben Fry, later created Processing, a digital sketchbook where designers and artists could code. As documented in AIGA Eye on Design’s oral history of Processing, it became both a software environment and a worldwide creative-coding community. In parallel, the dot-com boom produced the commercial variant: companies needed people who could move between technical infrastructure and creative intent.
2005–2015: the agency golden age. Arduino made hardware experimentation more accessible. openFrameworks and Cinder gave creative coders professional tools. Flash turned the web into an expressive playground. Agencies such as R/GA and Wieden+Kennedy, alongside studios such as Fake Love, helped build the experiential-marketing industry around creative technologists. Interactive installations, projection mapping, and sensor-driven brand experiences made “Creative Technologist” a role people could apply for, even when few people outside the field understood it.
2015–2022: fragmentation. The role splintered as product companies absorbed parts of it. Amazon used Design Technologist. Google used UX Engineer. Startups used Creative Developer. Product-focused branches moved toward what the industry now frequently calls Design Engineer. The artistic branch continued independently, from large-scale data sculpture to small experimental internet communities.
2022–now: the AI renaissance. Companies suddenly hold technologies whose cultural and experiential meaning has not yet been written. The capability that Experiments in Art and Technology cultivated in 1966 — sitting with a new technology before its use cases calcify and finding something meaningful in it — has become scarce again.
Image Credit: Diagram created by Ioana Teleanu, representing the timeline of Creative technology
The pattern across these decades is consistent: every time a genuinely new technology arrives — video, computation, the web, physical computing, AI — the people who figure out what it means are often the ones who treat it as a medium rather than just a tool. The names change. The disposition does not.
How it maps against adjacent roles
Where does this sit relative to the other roles emerging around design and technology?
Here is my attempt at an ontology.
Image Credit: Diagram created by Ioana Teleanu, representing spectrum of Creative technologists
Creative Technologist: the broadest and most experimental role. It combines technology, creativity, and strategy across hardware and software, installations and browsers, art and advertising. It is comfortable with the question, “What could this technology mean?” before anyone knows what to build. Google Creative Lab is one archetype: its roles have described work translating early-stage technologies into tangible, engaging experiences.
Design Technologist: the product-focused version. Companies such as Amazon and eBay have used this title for roles involving heavy prototyping, design systems, and UX engineering. It is generally more structured and less open-ended.
Design Engineer: the most production-oriented version. It combines product design, front-end code, and the craft of shipping interfaces. Companies such as Vercel, Stripe, Cursor, and Lovable have helped make the title increasingly legible in product teams.
Image credit: Computer Graphic by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
The boundaries are porous, but the orientation differs. The Creative Technologist asks, “What could this mean?” The Design Engineer asks, “How do we ship this well?” One writes the first draft of a technology’s meaning; the other makes sure the final draft is crafted.
Compensation is difficult to compare because the titles describe inconsistent scopes. A Google Creative Lab listing, for example, advertised a US base salary range of $162,000–$247,000, while broad salary aggregators combine very different kinds of Creative Technologist roles. The more useful conclusion is not that one title is inherently more valuable than another, but that organizations pay more consistently for roles whose production responsibilities are already legible.
But I think that’s about to change.
Why this role is having a moment
Three things are converging.
First: AI needs first drafts. Every company suddenly has access to technologies whose obvious use cases haven’t calcified yet. Models drop monthly. Capabilities shift weekly. And the question inside every organization is exactly the one Creative Technologists are trained to answer: what does this mean for us? Tina describes the actual brief at Google: a new model drops internally, and the ask is some version of “help people feel something other than dread about this”. That is the job now, at every company.
Image credit: Computer Graphic by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
Second, AI has lowered parts of the technical barrier, democratizing the technical layer. The earlier Creative Technologist often needed Processing, openFrameworks, C++, custom shaders, and hardware expertise. Those barriers kept the role relatively niche. A new generation can prototype with coding agents and generative models, although expertise still determines whether those prototypes become robust, responsible experiences. Adobe’s recent report, “The evolving role of the Creative Technologist,” describes the role as connective tissue across creative, engineering, marketing, and other teams — and as a missing layer in many enterprises.
Third: the doing is being celebrated. Tina again: “My fellow CTs are being flown out to give talks, poached mid-job with huge pay bumps, and inundated with DMs from startups begging them to find a use for their product.” The people who were building weird internet art for years are suddenly the most in-demand profile in tech. Product teams at Google. Design systems at Apple. Experimental storytelling at A24 in partnership with DeepMind.
The margins moved to the center.
Will we all become Creative Technologists?
Here is the question behind the question, and my current answer: not necessarily in title, but increasingly in how we relate to technology.
Tina makes an observation that stays with me:
“Today, kids are building entire worlds in Roblox like it’s a normal extension of playing. People are making little tools for their friends, their classrooms, or their own weird niche problems. No one waits for permission or funding or someone to translate their idea into code. Coding just feels like… a thing people do now.”
Her conclusion is that “Creative Technologist” may become less of a mutant profession that requires explanation and more of a way of relating to the most pervasive medium on earth.
That’s the real thesis. The Creative Technologist was never really a job title, it was an early name for a relationship to technology that’s now becoming universal: technology not as an industry you work in, but as a medium you think with.
Image credit: Computer Graphic by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
If you’ve been following this newsletter, you’ll recognize the pattern. The vibe-coded portfolio issue: designers shipping real products as self-expression. The Design JD issue: companies asking designers to “stay close to the models” and “invent patterns that feel native to AI”. The Forward Deployed Designer issue: designers embedding with teams to write the first draft of a solution. All of these are the Creative Technologist archetype leaking into every creative role.
A widely cited Gartner finding reported that 41% of employees already function as “business technologists,” creating technology or analytics capabilities outside traditional IT departments. The category is broader and more operational than creative technology, but the underlying trajectory is indicative: making with technology is no longer confined to a specialist enclave.
What this means for you
You don’t need to change your title. You need to notice whether you’re relating to technology as an industry or as a medium.
The industry relationship: you follow the tools, learn what you must, wait for the use cases to be defined, and then execute within them.
The medium relationship: you sit with new technology before its meaning has crystallised. You build small things to understand it viscerally. You ask what it could mean, not just what it does. You use it to say something.
The second relationship is what Tina found through nightclubs and net art. It’s what Blair Neal describes as choosing technologies “in thoughtful ways that honor the person experiencing something”. It’s what I keep trying to practice with every experiment I run and every “unsolicited” prototype I build.
It is learnable. It can start with one small project in which you use technology to say something, instead of simply shipping something.
That is the whole practice. The title is optional.
Image credit: END by Ioana Teleanu, created with AI assistance, Midjourney, 2026.
The company’s brand matters, but the owner’s visibility is the multiplier — and nearly half of business owners have no presence in the places AI treats as credible.
Key Takeaways
Companies where both the owner and the business are visible to AI saw a 2.5% year-over-year traffic increase, while those where both were invisible dropped more than 28% — a 30-point swing driven entirely by whether AI could identify a credible human behind the company.
Closing the gap isn’t a social media or SEO problem but an entity recognition one, solved by showing up in the third-party sources AI trusts: published articles, podcast interviews, speaking engagements, industry directories and local press.
You’re doing the work. The phones are ringing and your reviews look good. But you’ve noticed that your leads are not the same as they were last year. Referrals that used to flow in steadily have slowed as well. You’re not losing deals. You are losing the opportunity to compete for them like you used to.
The number that should concern you: 46%. I studied 400 companies across five industries. That’s the percentage of business owners who are completely invisible to AI. Not underperforming. Not dropping to page two. Gone. When a prospect asks ChatGPT, Perplexity or any AI assistant for a recommendation, nearly half of all business owners I studied are invisible in the answer.
And here’s the part that should surprise you: Your company may show up, but if the owner behind it is not visible, AI treats the business differently. The algorithm appreciates the company info but craves information about the owner or key person in the business — who is the human behind the brand and are they credible?
The gap that nobody is talking about
Companies where both the owner and the business were visible to AI saw an average year-over-year traffic increase of 2.5%. Companies where both were invisible? Down over 28%. That’s a 30% difference — same industries, same time frame. The difference is whether the person behind the company had any presence in places AI considers trustworthy.
On the surface, a 2.5% increase seems minimal. However, Gartner research predicts that organic traffic to websites will drop by 25% this year. Over the next three years, that kind of gap translates into millions of dollars in revenue the invisible owners never enter their sales funnel — not because the work was bad, not because the market or economy shifted, but because humans and machines couldn’t see who was behind the company. This is not a marketing problem or a traditional SEO problem.
I know what you’re thinking: “So I need to post more on social media.” Nope. This is an entity recognition problem. AI doesn’t really care about your Instagram reels or TikTok followers. It cares whether you are credible on the platforms AI approves as relevant to your expertise and authority. The venues change often, but the basics include published articles, podcast appearances, speaking engagements, industry directories and local press. The common thread: places where you are findable and verifiable.
Think of it this way: Would you hire a contractor with no reviews, no references and no one who could vouch for them? AI works the same way. It loves third-party signals of trust.
The owner is the multiplier
Here’s what surprised me in the research: The company’s brand visibility matters, but the owner’s visibility is the multiplier. A business with a strong brand and an invisible owner underperforms a business with a strong brand and a visible owner or subject-matter expert — every time. The owner’s visibility doesn’t just add to the company’s credibility; it amplifies it.
This makes sense if you think about it from the customer’s point of view. People want to know who they’re trusting with their money, their home, their family’s health. A faceless logo doesn’t answer that question. A person does. AI is simply reflecting what humans have always deferred to: I trust people more than brands.
What invisible owners get wrong
Most invisible owners are busy running their business. They’re not hiding on purpose. They assume their work speaks for itself. They’ve convinced themselves that marketing can handle visibility for the company.
But the world has shifted. Your prospects aren’t searching on Google alone anymore — they’re asking AI to help them decide. And AI builds its recommendations from a variety of sources and trust signals most business owners aren’t knowledgeable about.
The good news is that you don’t need to become a content machine. You don’t need to go viral. You need to exist in the places that matter to AI. Get your name in a local business journal with your point of view related to your industry. Show up on someone else’s podcast. Speak at your Rotary club or chamber event. Film it with your phone and post it to LinkedIn and YouTube. Share what you know in a way that helps people. Forget the sales pitch. Provide genuine value. When you teach, you build authority. When you build authority, AI pays attention.
The question you need to ask yourself
If someone asks an AI assistant to recommend a business like yours in the area, does your name show up? Not your company’s name — your name. Check it now.
The data is clear. When the owner is invisible, the company pays the price. When the owner is visible, everything compounds: trust, referrals, traffic, revenue. You built the business. You hired the team. You took the risk. The one thing you need to focus on now? Let the people — and the machines — know who’s behind it all.
That’s the invisible owner problem. And 46% of you are living it right now. The good news is that visibility isn’t reserved for people with PR teams and huge marketing budgets. It’s available for any owner willing to step out from behind their logo and be known for what they do.
VP of Brand Communications at Thrive Internet Marketing Agency and creator of the Business Visibility Index. Author of Uninvisible and TEDx speaker. I help business owners become visible to AI systems — building authority that gets them recognized and recommended by name.
Snap Inc. removed wholly AI-generated videos from recommendation eligibility on Spotlight, a change the company said took effect during July 2026 and published on July 31, 2026. Content edited with the platform’s own AI creative tools remains eligible and carries transparency indicators.
The change was set out in a post on the Snap Inc. Newsroom titled Rewarding Authentic Creativity on Spotlight, published on July 31, 2026 without a named spokesperson. According to the company, the update alters how its recommendation systems treat synthetic video in the short-form feed that competes with TikTok and Instagram Reels.
The operative sentence is narrow and specific. According to Snap, “As of this month and going forward, wholly AI-generated videos will no longer be eligible for recommendation on Spotlight.” The wording places the restriction on recommendation, not on upload. Nothing in the post states that such videos are removed, blocked at submission, or subject to account penalties.
What the policy covers and what it leaves alone
Two categories emerge from the announcement. Videos generated entirely by machine lose access to the recommendation surface. Videos that a person shot and then edited with generative tools do not.
According to the company, “content that has been enhanced or edited using Snapchat’s AI creative tools will continue to be eligible for recommendation and importantly include transparency indicators.” That sentence does two things at once. It preserves distribution for creators who use Snapchat features such as Imagine Lens, Animate It and AI Clips inside otherwise human-shot material, and it commits the platform to marking that material for viewers.
The post does not define the threshold at which enhancement becomes generation. It does not say whether third-party generative tools receive the same treatment as Snap’s own, nor whether a video assembled from stock footage and synthetic voiceover falls inside or outside the exclusion. Those definitional questions determine how much inventory the policy actually touches, and the announcement leaves them open.
Snap framed the position explicitly against a reading that it opposes generative tools altogether. According to the company, “This is not about rejecting AI. We know that for some, AI plays an important part of the creative process, and we believe it can unlock incredible new forms of expression.”
The contributor figure
The single quantitative disclosure in the post concerns supply, not consumption. According to Snap, the number of unique Spotlight contributors globally rose more than 120 percent compared with the prior year, a figure carrying a footnote in the original text.
That number matters because it describes the pool the recommendation system draws from. A feed with a rapidly expanding contributor base has more human-originated material available to rank, which lowers the cost of excluding a category of supply. The company did not disclose how many videos or what share of submissions the new rule affects, nor did it publish a baseline for the prior year’s contributor count.
The announcement contains an unusual admission for a platform policy statement. According to Snap, “No detection system is perfect, but our goal is simple: keep Spotlight a place where authentic creativity has the best opportunity to be discovered.”
No technical detail accompanies that sentence. The post names no watermarking standard, no provenance protocol, and no detection vendor. It does not say whether the system reads C2PA metadata, checks for cryptographic watermarks, or relies on classifier models trained on output signatures. The transparency indicators mentioned for AI-edited content are described only by function.
That gap is consequential because the enforcement mechanism determines the error profile. A provenance-based system catches content produced with cooperating tools and misses everything else. A classifier-based system produces false positives against unusual but human-made footage. Snap disclosed neither approach.
Spotlight sits inside the advertising inventory
The commercial context is not incidental. Spotlight has become a substantial share of what Snapchat sells.
Those figures sat within a quarter where revenue reached $1.529 billion, up 12 percent, while advertising revenue grew 3 percent to $1.24 billion. The gap between total and advertising growth had been widening for several quarters, with subscription products carrying an increasing share. Snap disclosed in July 2026 that its subscription business had passed 25 million subscribers across Snapchat+, Lens+, Platinum, Memories Storage and Creator Subscriptions.
Snap’s approach differs from both. It is neither a labelling requirement nor a user preference. It is a ranking exclusion applied by the platform, without an opt-out described for viewers who might want synthetic content surfaced.
Why the timing draws attention
The problem the announcement addresses has been measured repeatedly over the past year, and the measurements have grown more precise.
There is a regulatory clock running in parallel. Transparency obligations under Article 50 of the EU AI Act became applicable on August 2, 2026, two days after the Snap post, carrying penalties of up to 15 million euros or 3 percent of worldwide annual turnover for non-compliance with the marking and disclosure duties. The Snap announcement makes no reference to any regulation, and the transparency indicators it describes are presented as a product choice rather than a compliance measure. The calendar proximity is a fact about timing, not a stated cause.
Brand safety measurement on the surface has a history. An independent study cited when Snapchat expanded its brand safety partnership with Integral Ad Science in 2024 found 99 percent of the platform’s public content within Spotlight and Creator Stories to be brand-safe. That measurement predates the current wave of generative video and did not test for synthetic origin.
The ranking change alters the composition of the environment adjacent to Spotlight advertising without altering any campaign control. No new exclusion setting, targeting parameter or reporting dimension was described. Buyers cannot currently filter Spotlight inventory by whether adjacent content carries a transparency indicator, and Snap did not say whether such a control is planned.
December 16, 2024 – Snapchat announces a unified monetisation programme extending payouts to Spotlight videos over one minute, citing a 25 percent rise in Spotlight viewership
Who: Snap Inc., publishing through its corporate Newsroom without a named spokesperson, addressing creators posting to Spotlight and the advertisers buying inventory adjacent to that content.
What: An update to Spotlight recommendation systems under which wholly AI-generated videos lose eligibility for recommendation, while content enhanced or edited with Snapchat’s AI creative tools remains eligible and carries transparency indicators. The post disclosed that unique Spotlight contributors globally rose more than 120 percent year-over-year and acknowledged that no detection system is perfect.
When: Published July 31, 2026, with the company stating the change applies as of that month and going forward. It follows a June 2026 advertising suite launch and precedes by two days the date on which EU AI Act Article 50 transparency obligations became applicable.
Where: Globally, across the Spotlight recommendation surface inside Snapchat.
Why: Snap stated that low-quality, repetitive AI-generated content is becoming increasingly common across the internet and that it wants Spotlight to remain a place where people discover work from real people. Spotlight accounts for a large share of platform viewing time and of the impression supply that has been compressing effective CPMs, making the composition of that feed a commercial question as well as an editorial one.
Luís Rijo has written PPC Land daily since founding it in 2016. Over 10,000 articles, funded by readers, no sponsored coverage. Tips and corrections: [email protected]